 Elias Nieminen
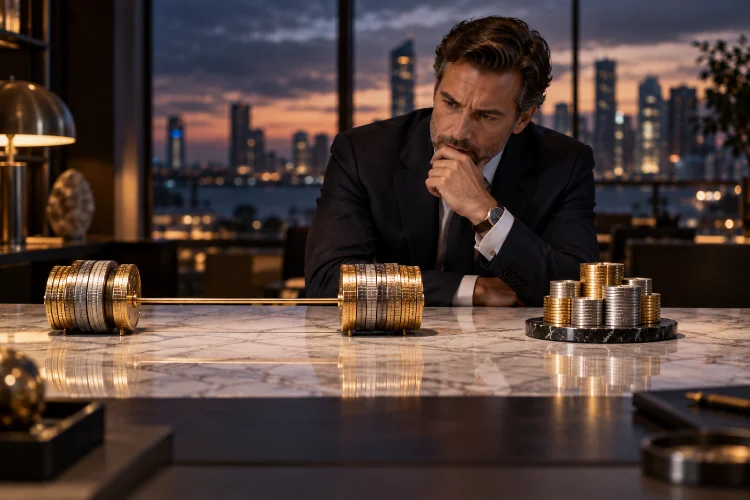
Two gilt portfolios can have almost the same duration and still behave very differently when the yield curve starts moving.
One may concentrate investments around a single maturity range. Another may combine very short and very long gilts while holding almost nothing in between.
On paper, their average interest-rate sensitivity could look similar. In practice, changes in short-term rates, long-term yields, curve shape, and market volatility can produce surprisingly different results.
That is the idea behind barbell versus bullet gilt portfolios in volatile markets.
A bullet portfolio concentrates exposure around a particular maturity or duration target. A barbell spreads exposure between short- and long-dated securities.
CFA Institute notes that, for a given duration, the barbell structure generally has greater convexity because its cash flows are more widely dispersed.
Neither structure is universally superior.
The better choice depends on the investor’s view of the UK yield curve, liquidity needs, reinvestment risk, volatility tolerance, and what role gilts are supposed to play in the wider portfolio.
What Is a Bullet Gilt Portfolio?
A bullet portfolio concentrates most of its bonds around one part of the maturity curve.
Suppose an investor wants roughly ten-year exposure.
A simple bullet structure might hold several gilts maturing between eight and twelve years, with most of the portfolio’s duration concentrated around that area.
The result is relatively focused interest-rate exposure.
If yields in that maturity segment fall, the portfolio can benefit directly. If they rise, most of the portfolio is exposed to the same part of the curve.
This makes bullet portfolios useful when investors have a specific investment horizon or a relatively strong view about one maturity sector.
They can also work well for liability matching.
If a future expense is expected around 2036, concentrating government-bond cash flows around that period may be more logical than owning large amounts of both two-year and twenty-year securities.
The simplicity is attractive, but concentration creates curve risk. If the targeted section of the gilt market performs poorly, there is little exposure elsewhere to compensate.
How a Barbell Portfolio Works
A barbell does almost the opposite.
Instead of concentrating around an intermediate maturity, it combines short-dated and long-dated gilts.
Imagine a portfolio containing short gilts maturing within two or three years alongside long gilts maturing in fifteen or twenty years.
The short side offers liquidity and frequent opportunities to reinvest.
The long side provides more duration and greater sensitivity to falling long-term yields.
Together, the two ends can be weighted so that the total portfolio duration resembles an intermediate-duration bullet.
For example, a barbell combining short and long securities could theoretically have a duration similar to a portfolio concentrated around seven or eight years.
But matching duration does not make the portfolios equivalent.
Their exposures to different parts of the yield curve remain very different.
CFA Institute describes the barbell as having greater convexity than a duration-matched bullet. That becomes particularly relevant when yield movements are large rather than tiny.
Duration May Match, but Convexity Does Not
Duration approximates how much a bond’s price should change when yields move.
Convexity goes one step further by recognising that the relationship between bond prices and yields is curved rather than perfectly linear.
This distinction matters most when rates move substantially.
Suppose two portfolios both have a duration of approximately seven years.
One is a bullet concentrated around intermediate gilts.
The other is a barbell containing short and long gilts.
If yields undergo a perfectly parallel and very small change, their initial price responses may look fairly similar.
When yield changes become larger, the greater convexity of the barbell can become more valuable.
In general, positive convexity means the portfolio gains slightly more when yields decline than the corresponding amount it loses when yields rise by the same amount, all else equal.
But greater convexity is not free.
Long-dated gilts can be highly volatile, and the barbell’s short side continually creates reinvestement exposure.
So investors should not simply conclude that more convexity automatically means less risk.
Barbell Portfolios Can Benefit From Curve Flattening
The shape of the yield curve matters enormously.
CFA Institute identifies three main yield-curve risk factors: changes in the overall level of yields, changes in slope, and changes in curvature.
A barbell is often associated with a view that the yield curve will flatten.
Suppose short yields decline while long yields remain relatively stable.
The short part of the barbell can benefit, while the long side retains its yield and duration exposure.
Alternatively, long yields might fall more than intermediate yields, creating strong gains at the long end.
But a barbell can become uncomfortable during some steepening environments.
For example, imagine long gilt yields rise sharply because markets demand more compensation for inflation or long-term uncertainty while short rates remain relatively stable.
The long end of the barbell can then suffer significant losses.
This is why investors need to distinguish between a bull steepener, bear steepener, bull flattener, and bear flattener rather than simply saying “the curve moved.”
The location of the move matters.
Bullet Portfolios Can Be Stronger in a Steepening View
A bullet structure can be attractive when an investor expects the part of the curve around the portfolio’s target maturity to outperform the two extremes.
CFA Institute’s fixed-income framework traditionally associates bullets with strategies designed to benefit from certain steepening movements, while barbells are more commonly linked to flattening views.
Imagine an investor holds intermediate gilts while long-term yields rise substantially.
A bullet portfolio could avoid some of the damage experienced by a barbell’s long-duration component.
At the same time, it may offer more locked-in yield than a portfolio dominated by short securities.
This middle-ground exposure can feel particularly useful when the investor has little conviction about the extremes of monetary policy.
However, the result depends on where the steepening occurs.
If intermediate yields rise more aggressively than both the short and long ends, a bullet can underperform.
Yield-curve trades are therefore relative rather than absolute.
The Bank of England publishes daily estimated nominal and real UK government bond curves, allowing investors to observe how yields vary across maturities rather than treating “the gilt yield” as one number.
Compare Reinvestment Risk With Price Risk
The biggest practical difference between the structures may not be convexity at all.
It may be what happens to the investor’s cash.
The short side of a barbell matures regularly.
That creates liquidity, but it also means cash must repeatedly be reinvested.
If rates fall sharply, those maturing gilts could be replaced at much lower yields.
The long side has the opposite problem.
It locks yields for longer, reducing reinvestment risk, but its market price can fluctuate dramatically before maturity.
A bullet balances these risks differently.
Intermediate gilts generally create less immediate reinvestment pressure than short bonds while producing less price volatilty than very long gilts.
For an investor planning a known withdrawal in eight years, that may be a sensible compromise.
For someone who wants substantial near-term liquidity plus a hedge against falling long-term rates, the barbell might be more useful.
The correct structure depends on when the capital will actually be needed.
Watch Carry, Yield and Curve Pricing
Portfolio structure cannot be assessed from duration alone.
Starting yield matters.
Imagine the short end of the gilt curve offers an unusually high yield while intermediate gilts yield considerably less.
A barbell allocation can capture some of that attractive short-term income while retaining long-duration exposure.
In another environment, intermediate gilts may offer the most attractive combination of yield and risk.
The Bank of England explains that UK yield curves reflect real rates, inflation expectations and risk premia, while forward rates embedded in the curve should not be treated as guaranteed predictions of future interest rates.
Investors therefore need to ask what is already priced.
A strategy may correctly predict falling Bank Rate yet still disappoint if gilt markets had already fully anticipated those cuts.
Carry and rolldown also matter.
A bond can generate return simply by ageing into a different part of an upward-sloping yield curve, assuming the curve itself remains broadly unchanged.
That means tactical analysis should compare the expected total return of each structure, not just the direction of rates.
Stress-Test Non-Parallel Curve Moves
One of the most useful exercises is to stop assuming every yield moves by the same amount.
Consider three scenarios.
In the first, all gilt yields fall 0.75 percentage points.
In the second, short yields fall one point while long yields barely move.
In the third, short yields remain stable while 20-year yields rise one point.
A simple duration measure handles the first scenario reasonably well.
The second and third require understanding where duration sits along the curve.
This is where key rate duration becomes useful. CFA Institute notes that key rate durations can measure how sensitive a portfolio is to changes at specific points along the yield curve.
A barbell naturally has more sensitivity at the short and long ends.
A bullet concentrates sensitivity around its target maturity.
Stress testing those exposures makes the risk much easier to understand than simply saying both portfolios have “seven years of duration.”
For volatile markets, that distinction is critical.
Tax and Liquidity Can Change the UK Decision
Individual gilts also have a useful UK tax characteristic.
HMRC states that disposals of qualifying gilt-edged securities are exempt from Capital Gains Tax for individuals.
That can affect how investors choose between specific gilts in taxable accounts, especially where low-coupon bonds trade below redemption value.
Tax treatment should not determine whether the portfolio is a barbell or bullet, but it can influence security selection within each structure.
Liquidity matters too.
Short-dated gilts can provide scheduled access to capital as they mature, while a long-dated security may need to be sold at a potentially unfavourable market price if cash is required unexpectedly.
The UK Debt Management Office confirms that conventional gilts normally pay fixed coupons every six months and repay principal at maturity.
A practcial portfolio design should therefore begin with actual spending requirements before adding tactical curve views.
A Hybrid Approach Can Reduce Forecast Risk
Investors do not necessarily have to choose a pure barbell or pure bullet.
A portfolio could hold short maturities for liquidity, a meaningful intermediate allocation for stability, and a smaller long-duration position for convexity and rate sensitivity.
This produces a less extreme structure.
It may sacrifice some potential upside if one yield-curve forecast is exactly correct, but it also reduces dependence on that forecast.
Another option is to maintain a strategic bullet-like core while tactically adding short or long gilts when curve pricing becomes unusually attractive.
That can be easier to manage than rebuilding the entire bond portfolio every time rate expectations change.
The broader lesson is that curve curviture, duration and convexity should be viewed together.
No single statistic describes the entire risk profile.
Barbell versus bullet gilt portfolios in volatile markets is ultimately a choice about where you want interest-rate risk to sit.
A bullet concentrates exposure around one maturity range and can fit specific liabilities or intermediate-rate views. A barbell combines short-term liquidity with long-duration sensitivity and generally offers greater convexity for a similar overall duration.
Neither structure consistently wins.
Flattening, steepening, inflation shocks, Bank Rate expectations, carry, and reinvestment conditions can all change the result. A duration-matched comparison is only the beginning; investors also need to examine key-rate exposure and curve shape.
Before choosing either structure, map when the money will be needed, stress-test several non-parallel yield moves, and compare the current yields available across the gilt curve.
Use tactical positioning to complement those objectives rather than letting one interest-rate forecast control the portfolio.